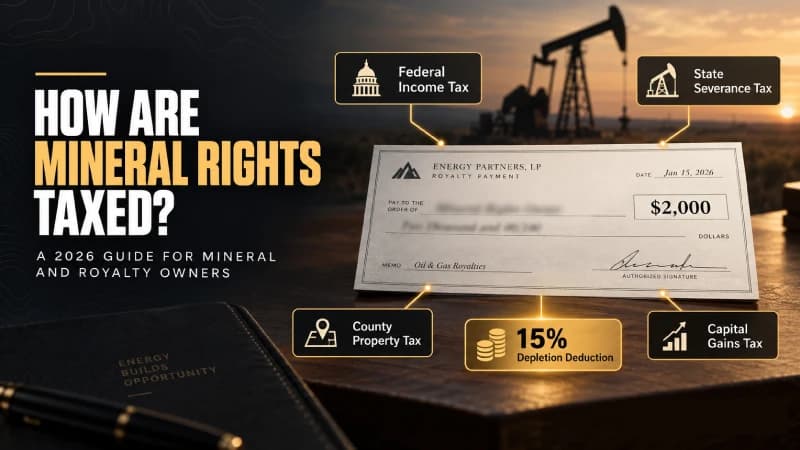
A Texas royalty owner gets a $2,000 check in January. By April, four different governments want a piece of it - and one of them already took theirs before the check was even cut.
Federal income tax. State severance tax. County property tax. And if the owner ever sells, capital gains tax on top.
Most mineral owners know they owe something. Almost none know exactly how much, to whom, or which deductions they're leaving on the table. The depletion deduction alone - a 15% write-off that the tax code specifically designed for mineral owners - gets missed on thousands of returns every year because no one told the owner it existed.
This guide walks through all four taxes in the order you will actually encounter them, with the forms, the rates, and the worked math, so the next check stub you open isn't a mystery.
Key Takeaways
- Royalty income is taxed as ordinary income which is reported on Form 1099-MISC and filed on Schedule E, not at the lower capital gains rate.
- Severance tax is already deducted from your check before it arrives. In Texas, that is 4.6% on oil and 7.5% on gas.
- The depletion deduction (typically 15%) is the most commonly missed tax benefit for mineral owners. It must be claimed on the return; the IRS does not apply it automatically.
- Inherited minerals receive a stepped-up basis to fair market value at the date of death, which can dramatically reduce capital gains tax on a later sale, but only if the value is documented.
- Producing minerals are subject to county property tax, and the appraisal can be protested annually. In Texas, the protest deadline is generally May 15.
The Four Major Tax Areas at a Glance
| Tax | Who levies it | When it applies | How it usually reaches you |
|---|---|---|---|
| Federal income tax | IRS | On royalty, bonus, and other taxable mineral income | Reported annually using the appropriate tax forms; royalty payments are generally reported on Form 1099-MISC, while working-interest payments may be reported differently. |
| Severance (production) tax | State | When oil or gas is produced and sold | The tax is generally paid by the producer or purchaser and may be reflected as a deduction from the owner's payment, depending on the applicable arrangements. |
| Ad valorem property tax | County or local district | Generally once the interest is producing | An annual bill from the county appraisal district |
| Capital gains tax | IRS, and some states | Only when the interest is sold | Filed in the year of the sale |
Are Mineral Rights Taxable
Yes, but only some of the time, and the answer turns almost entirely on whether the minerals are producing.
- Non-producing minerals generally do not generate income tax from production because there is no production income. Whether they are subject to property tax depends on state and local law and how the interest is valued.
- Producing minerals may result in federal income tax, state production or severance tax, and local property tax, depending on the state and the type of interest. Capital-gains tax treatment generally applies when the interest is sold.
Selling an interest triggers capital gains tax whether or not it was ever producing.
If Your Minerals are in Texas
Understanding how mineral rights are taxed is especially important for Texas mineral owners because the state does not impose a personal income tax, while production and property taxes can still apply.
- There is no Texas state personal income tax, so royalty income is subject to federal income tax but not to a state income tax. Owners in states such as Oklahoma, New Mexico, Colorado and North Dakota do face a state income tax layer.
- Severance tax runs 4.6 percent on oil and 7.5 percent on natural gas of market value, per the Texas Comptroller. Confirm these rates against the Texas Comptroller's current schedule before relying on them — legislative sessions can adjust them.
- Mineral interests become taxable for property tax purposes on January 1 of the year following first production of the unit.
- In Texas, a mineral interest with a taxable value of less than $500 is exempt, and mineral interests owned by the same person in a taxing unit are aggregated when determining the value for this exemption. This threshold is set by Texas Tax Code §11.145 - verify it has not been revised in a recent legislative session.
- Appraisal protests are generally due by May 15, or 30 days after your appraisal district's notice, whichever is later.
Tax 1: Federal Income Tax on Royalty Income
This is the tax most mineral owners think of first, and it is also the one with the most moving parts.
Payers generally report gross royalty payments of $10 or more from oil, gas, or mineral properties on Form 1099-MISC, Box 2. The IRS instructions state that these amounts are reported before reductions for severance and other taxes withheld and paid. A royalty owner holding a non operating interest normally reports that income on Schedule E, where it is taxed at ordinary income rates rather than at the lower long term capital gains rates.
Two distinctions matter here.
Royalty Interest Versus Working Interest.
A royalty owner does not pay drilling or operating costs and normally reports income on Schedule E at ordinary income rates. A working interest owner shares in costs, generally reports on Schedule C, and may owe self-employment tax. If you converted a royalty position into a working interest or participated in a drilling program, the filing path is different. You can consult a CPA.
Passive Income Classification.
Whether royalty income counts as passive (for the passive activity loss rules), qualifies for the Section 199A deduction, or triggers the 3.8% net investment income tax depends on the specific facts of your ownership. Royalty income from a purely passive non-operating interest is generally not treated as qualified business income. These questions are fact-specific and worth putting to a tax professional rather than assuming.
What Actually Comes out of a Royalty Check
Here is what a typical month looks like for a Texas gas well:
| Line | Amount |
|---|---|
| Your share of gross production value | $2,000.00 |
| Less Texas severance tax at 7.5 percent | ($150.00) |
| Less post production costs at 8 percent, where the lease allows them | ($160.00) |
| Net payment to you | $1,690.00 |
Only one of those two deductions is a tax. Whether post production costs can be charged against your royalty at all depends on the wording of your lease, which is why the royalty clause matters more than almost anything else in it.
Payers differ on whether the annual 1099-MISC reports the gross or the net figure, so keep the monthly check stubs rather than relying on the 1099 alone. If the volumes on your check stub do not match what you expected, Mineral View's well-level production data lets you compare the operator's reported production against the state's official records before filing. Your check already has severance tax taken out. The 1099 may or may not match what you actually received - the check stubs are your source of truth.
The Depletion Deduction
Minerals are a wasting asset. Every barrel produced is a barrel that will never be produced again, and the tax code recognizes this through the depletion deduction.
Two methods exist. Cost depletion recovers the owner's basis in the property in proportion to the reserves produced. Percentage depletion for oil and gas is generally 15%, although special rules can apply to marginal production and other qualifying circumstances. Owners who qualify for both are generally entitled to claim whichever produces the larger deduction.
An illustration. On $24,000 of gross royalty income for the year, percentage depletion at 15% would be $3,600, reducing taxable royalty income to $20,400 before any other deductions. That $3,600 also reduces your basis in the property, which matters later if you sell.
Percentage depletion is subject to several limitations. For oil and gas properties, the deduction generally cannot exceed 100% of taxable income from the property and is also subject to a 65% limitation based on the taxpayer's adjusted taxable income. It also generally cannot be claimed against a lease bonus.
Depletion is frequently missed by owners filing without help, and it is not trivial. The guide to royalty tax deductions covers the mechanics.
If you receive royalty income and your tax preparer has never mentioned the depletion deduction, ask about it. It is specifically designed for mineral owners, and missing it means overpaying.
What About the Lease Bonus
A lease bonus, the upfront payment for signing an oil and gas lease, is generally taxable as ordinary income in the year received. It is not a capital gain, even though it can feel like a payment for something sold. As noted above, percentage depletion generally cannot be claimed against it.
How to Report Royalty Income on your Tax Return
In broad terms, and subject to your own circumstances:
- Form 1099-MISC, box 2 is where royalty payments are usually reported to you.
- Schedule E, Part I is where a non operating royalty owner normally reports that income, along with depletion, production taxes and other allowable expenses.
- Schedule C applies instead where you hold a working interest and are treated as being in the trade or business, and self employment tax generally follows.
- Multiple properties are generally reported separately rather than lumped together, because depletion limits are applied on a property by property basis.
If you own interests in more than one state, a non resident state return may also be required in the producing state even where you owe nothing.
Putting It All Together: From Production to Tax Return
Most guides show either how royalties are calculated or how they are taxed, but not the full path from wellhead to tax return. Here is a single year, simplified, for a Texas royalty owner with one producing gas well.
Annual Royalty-to-Tax Walkthrough
| Step | What happens | Amount |
|---|---|---|
| 1. Well produces gas | Operator reports annual production and sells at market price | — |
| 2. Gross royalty calculated | Your decimal interest × total revenue for the year | $24,000 |
| 3. Severance tax deducted at 7.5% | Operator withholds before cutting your check | ($1,800) |
| 4. Post-production costs deducted at 8% | Where the lease allows them | ($1,920) |
| 5. Net checks deposited over 12 months | What actually hits your bank account | $20,280 |
| 6. 1099-MISC issued (Box 2) | May report $24,000 (gross) or $20,280 (net) — verify against stubs | varies |
| 7. Reported on Schedule E | Gross royalty income, with deductions listed separately | $24,000 |
| 8. Depletion deduction claimed (15%) | 15% of gross royalty income | ($3,600) |
| 9. Severance tax deducted on Schedule E | The $1,800 already withheld, now claimed as a deduction | ($1,800) |
| 10. Taxable royalty income | What is actually subject to federal income tax | $18,600 |
The owner deposited $20,280 in cash but owes federal income tax on $18,600, not on the $24,000 the 1099 may show. The difference between those three numbers is where most filing errors occur. Every line above has a paper trail: the check stubs support steps 2–5, the 1099-MISC supports step 6, and Schedule E ties steps 7–10 together.
Note: This walkthrough is illustrative. Actual figures depend on your lease terms, production volumes, commodity prices, and individual tax situation. Post-production cost deductibility depends entirely on the language of your lease.
Tax 2: State Severance Tax
Severance tax is charged by the state on the value or volume of oil and gas severed from the ground. It is the tax most owners never file for, because it is almost always deducted from the royalty check before payment.
Texas is a useful reference point. The Texas Comptroller sets the crude oil production tax at 4.6 percent of the market value of oil, and the natural gas production tax at 7.5 percent of the market value of gas, with condensate taxed at 4.6 percent. Reduced rates apply to qualifying production, including a 2.3 percent rate for certain enhanced oil recovery projects.
Rates and structures differ substantially across producing states. Oklahoma, New Mexico, North Dakota, Colorado, Wyoming, Louisiana, and Pennsylvania all handle severance tax differently, some charge a flat percentage of market value, some stack multiple levies, and some (like Pennsylvania) use an impact fee instead of a traditional severance tax.
Several states also run incentive programs that reduce the rate for low-producing, high-cost, or newly completed wells. If you own interests outside Texas, check the producing state's published rate against the deduction on your check stub.
Severance tax is already gone before your check arrives. The line item on your stub is how you verify it was calculated correctly.
Tax 3: Ad Valorem Property Tax
In many producing states, a producing mineral interest is appraised and taxed as real property by the county or local taxing district, in much the same way a house is. The owner receives an annual bill even though they may never have set foot on the land.
For producing mineral interests, valuation commonly considers expected future production and other factors used under the applicable state's appraisal rules. Because appraisal methods vary by jurisdiction, the tax value may change as production and other valuation factors change. Non producing minerals are frequently not assessed at all, or are assessed at a nominal value, though this varies by state and county.
In Texas, appraisal districts commonly engage a specialist oil and gas appraisal firm to value mineral interests on their behalf, and the January 1 rule, the $500 exemption and the protest deadline noted earlier all apply.
Because appraisal practice is local, your county appraisal district is the authority on how a specific interest is valued and what exemptions and deadlines apply. The full breakdown, including how the Texas valuation is built and what happens if a bill goes unpaid, is in the dedicated guide to property taxes on mineral rights.
If your minerals are producing, expect a county property tax bill, even if you have never visited the land. The appraisal can be protested, and it is often worth doing.
Tax 4: Capital Gains When You Sell
How mineral rights are taxed also depends on what happens when an owner sells the interest, because the sale can create a taxable gain. If the interest was held for more than a year, that gain is normally taxed at long term capital gains rates, which are usually lower than the ordinary income rates that apply to royalty income.
Several things complicate this.
Basis
Gain is sale price less adjusted basis. Owners who purchased their minerals have a purchase price to work from. Owners who received minerals as a gift usually carry over the giver's basis, which is often much lower. Owners whose minerals came down through several generations frequently have no documented basis at all, which is a problem worth solving before a sale rather than after.
Inherited Minerals and Stepped-Up Basis
This is the single most valuable point in this article for anyone who inherited their interests.
Property inherited from a decedent generally takes a basis equal to its fair market value at the date of death, or at the alternate valuation date if the estate elected one. Minerals that had effectively no cost basis in the family's hands can therefore be reset to a much higher figure, which substantially reduces the taxable gain on a later sale.
The practical difficulty is proving that value years afterwards. Where a date of death valuation was never obtained, options generally include a retrospective appraisal by a qualified mineral appraiser, contemporaneous production and price records for the wells involved, and any estate inventory or estate tax return filed at the time. Establishing it while the records are fresh is far easier than reconstructing it a decade later.
What Inherited Mineral Owners Need to Know
The TCJA of 2017 roughly doubled the federal estate tax exemption, pushing it above $13 million per individual (indexed for inflation). Under the original legislation, that increase was scheduled to sunset after December 31, 2025, potentially cutting the per-person exemption to approximately half, around $7 million, adjusted for inflation.
Whether Congress extended, modified, or allowed the sunset to take effect matters directly to mineral owners for two reasons. First, a lower exemption means more estates that include mineral interests could be subject to federal estate tax. Second, the stepped-up basis discussed above (the single most powerful tax provision for inherited minerals) remains available regardless of the exemption level, but estate planning strategies built around the exemption threshold may need revisiting.
The Practical Step:
- Confirm the current exemption amount with a qualified estate planning attorney or CPA.
- If you inherited minerals recently, or expect to, the estate tax landscape as of 2026 may be materially different from what was in place when the interest was first acquired.
- A handful of states also impose their own estate or inheritance taxes at substantially lower thresholds than the federal exemption.
Depletion and Cost Recapture
Deductions taken in earlier years do not simply disappear. Depletion deductions generally reduce the property's adjusted basis and can affect the gain recognized on a later sale. The treatment of any previously deducted intangible drilling costs or other deductions depends on the type of interest and the applicable tax rules. This catches owners who assumed the whole gain would be taxed at the lower rate.
A Worked Example
Suppose a person inherits a producing mineral interest in Texas. The interest is valued at $125,000 on the date of the owner's death, establishing the heir's initial tax basis. Over the next several years, the heir receives royalty income and claims $18,000 in depletion deductions. The adjusted basis is therefore reduced to $107,000.
Five years later, the owner sells the mineral interest for $185,000.
Capital Gains Calculation
| Step | Amount |
|---|---|
| Date-of-death value and initial basis | $125,000 |
| Less: depletion claimed | ($18,000) |
| Adjusted basis | $107,000 |
| Sale price | $185,000 |
| Total gain | $78,000 |
Because the property was inherited, the owner is generally treated as having held it for more than one year, so a qualifying gain is generally treated as long-term rather than short-term capital gain. The $78,000 gain shown here is a simplified calculation; the actual taxable amount can change based on selling expenses, additional basis adjustments, and the specific tax treatment of the mineral interest.
The actual tax owed would depend on the owner's taxable income, applicable capital-gains rate, and other tax circumstances. Higher-income owners may also be subject to the 3.8% Net Investment Income Tax.
Note: This example is for illustrative purposes only. The figures are simplified and do not account for all possible tax adjustments, selling expenses, or individual circumstances. Actual tax treatment and liability may vary based on the mineral interest and applicable tax laws.
How to Report a Sale
The reporting form depends on the nature of the mineral interest and the transaction. A sale may involve Form 8949 and Schedule D, while Form 4797 can apply to certain business or property transactions and recapture amounts. An installment sale may be reported on Form 6252. This is an area where the reporting is genuinely technical and worth handing to a CPA.
Can a 1031 Exchange Defer the Tax
Possibly. Certain mineral interests may qualify as real property for Section 1031 like-kind exchange purposes, which could defer the capital gains tax. However, the 2017 tax law narrowed 1031 exchanges to real property only, and the IRS's 2020 final regulations (Treas. Reg. §1.1031) define "real property" more precisely than before. The timing rules are strict, with identification and closing deadlines that leave little room for error. This is not a strategy to attempt without specialist advice arranged before the sale closes.
State Treatment
Some states tax capital gains as ordinary income, some do not tax them at all, and a non resident selling minerals in a producing state may face a filing obligation in that state as well as at home. Texas owners selling Texas minerals have no state capital gains tax to contend with.
The gain on a mineral sale is measured from your adjusted basis, not from what you think the interest is "worth." If you inherited and never established a date-of-death value, that is the single most important task before listing.
Common Mistakes That Cost Mineral Owners Money
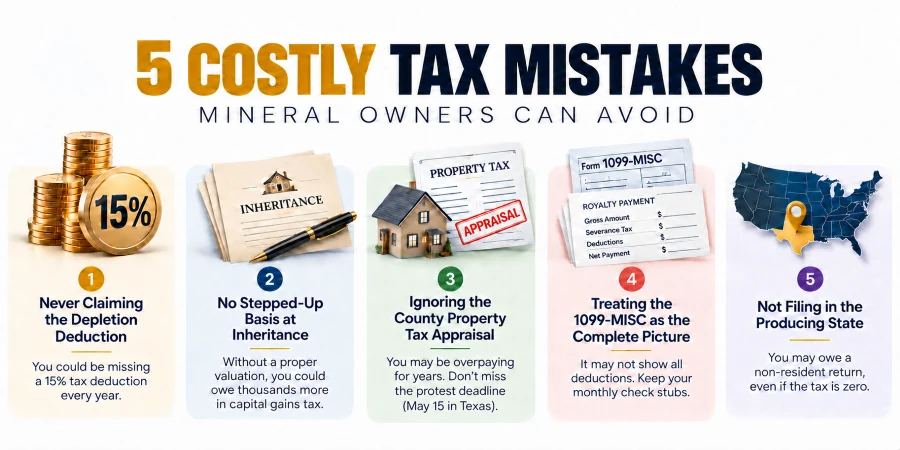
These are the errors that show up most often - each one is avoidable, and each one costs real dollars when missed.
1. Never Claiming the Depletion Deduction
Percentage depletion at 15% is available to qualifying royalty owners every year they receive production income. It is not automatic, it has to be claimed on the return. Owners who file without a preparer familiar with mineral interests miss it routinely, and the IRS does not send a reminder.
2. Failing to Establish Stepped-up Basis at Inheritance
The date-of-death value is what separates a $12,000 capital gains bill from a $45,000 one. Getting a valuation done at or near the time of inheritance is straightforward. Reconstructing it a decade later (from old production records, historical prices, and a retrospective appraisal) is expensive, uncertain, and sometimes impossible.
3. Ignoring the County Property Tax Appraisal
Producing mineral interests are appraised annually, and those appraisals can be protested. Owners who never open the notice or assume it is correct may be paying on an inflated valuation for years. The protest window is short (in Texas, generally May 15 or 30 days from the notice) and once it closes, you wait another year.
4. Treating the 1099-MISC as the Complete Picture
The 1099 may report gross or net, depending on the payer. Without the monthly check stubs showing severance tax, post-production deductions, and the actual net deposited, it is impossible to verify the 1099 or claim the right deductions.
5. Not Filing in the Producing State
Owners who live in one state but hold minerals in another often owe a non-resident return in the producing state, even if the net tax is zero. Skipping it can trigger penalty notices that cost more than a preparer would have charged.
Records Worth Keeping
Tax outcomes on mineral interests are decided largely by paperwork that owners are asked to produce years after the fact. Worth holding on to:
- Every 1099-MISC, and the monthly check stubs behind them. For owners managing multiple properties, Mineral View can also help organize and review production and ownership information alongside these personal tax records.
- The deed by which the interest was acquired, and the date.
- Anything establishing basis: a purchase agreement, an estate inventory, a date of death appraisal.
- Signed leases and any amendments, particularly the royalty and post production cost clauses.
- Recorded division orders and any decimal interest revisions.
- Annual county tax statements
For owners tracking several tracts across multiple counties, the hardest part is often not the tax rules but simply establishing what they own and what each interest produced. Mineral View's ownership and production data can help consolidate that information in one place.
Know What You Own Before Tax Season
Every tax question in this guide eventually comes back to the same starting point:
- What you own
- Where it is producing
- The income from your royalty payments
Whether you are reviewing a 1099, understanding changes in your royalty income, or documenting your ownership and basis, accurate ownership and production records are important.
Mineral View helps mineral and royalty owners review property records, track well-level production, and organize ownership details across multiple counties and states-all in one place.
Frequently Asked Questions
Do I Have to Pay Taxes on Mineral Rights?
Yes, if they are producing. Royalty income is subject to federal income tax, severance tax is usually deducted from your check before payment, and producing interests are typically assessed for county property tax. If they are not producing, there is usually no income tax and often little or no property tax.
Do You Have to Pay Taxes on Mineral Rights That Are Not Producing?
Generally no income tax, because there is no income. Many counties assess non producing minerals at little or no value, and in Texas interests worth under $500 in a taxing unit are exempt, but practice varies — the local appraisal district is the place to confirm.
How Can I Reduce Tax on the Sale of Inherited Mineral Rights?
The stepped-up basis is usually the single biggest factor. The taxable gain is measured from the fair market value at the date of death, not from what your parent or grandparent originally paid. Establishing and documenting that value is the practical task. Inherited property generally receives a holding period of more than one year for federal tax purposes, regardless of how long the beneficiary or decedent actually held it. All of this needs professional advice specific to your situation.
Is It Wise to Sell Your Mineral Rights?
That is a decision about your own circumstances rather than a tax question, though the tax bill is part of it. The considerations are covered in the guide on whether to sell mineral rights.
Is Oil and Gas Royalty Income Passive Income?
It depends on the facts and on which rule is being applied. Royalty income from a non operating interest is often treated as portfolio or passive income rather than as income from a trade or business, but the passive activity rules, the net investment income tax and the Section 199A deduction each test it differently. This is worth confirming with a CPA.
Do I Pay Self-Employment Tax on Royalties?
Generally no, for a non-operating royalty interest. Working interest income, on the other hand, usually is subject to self-employment tax.
Are Shut-In Payments and Delay Rentals Taxable?
Yes, they are generally taxable as ordinary income in the year received — not as capital gains. The exact treatment can depend on the lease wording and the nature of the payment, so review with a CPA if the amounts are significant.
Why Is Severance Tax on My Check When I Never Filed for It?
Because the operator or purchaser remits it for you. It is deducted from the gross value before your share is calculated. It should appear as a separate line on the check stub, and it can be checked against the state's published rate.
Important
This article is general information, not tax or legal advice, and mineral taxation varies significantly by state, by county and by the type of interest held. Understanding how mineral rights are taxed requires looking at more than royalty income alone. Production taxes, property taxes, depletion, basis, and the tax consequences of selling an interest can all affect the final outcome.
Because the rules vary by state and by the type of mineral interest, owners should review their specific situation with a qualified tax professional before making decisions. For Texas specifics, the Texas Comptroller of Public Accounts publishes current severance tax rates and protest procedures, and your county appraisal district is the authority on how a particular interest is valued for property tax.